
Cash-basis accounting records income and expenses when money actually changes hands. Accrual-basis accounting records them when a sale is earned or a bill is incurred, regardless of when cash lands in the bank. Most freelancers, sole proprietors, and small service businesses do fine on cash-basis. Once you carry inventory, take on investors, or cross the IRS gross-receipts threshold, accrual becomes the better, and sometimes mandatory, choice.
TL;DR:
- Small businesses under $32 million in gross receipts typically can choose between cash and accrual accounting, based on their cash flow cycle and inventory considerations.
- Switching from cash to accrual accounting involves filing IRS Form 3115 and managing a Section 481(a) adjustment, which can create a one-time tax impact.
- Businesses collecting payments over long cycles or with material inventory usually benefit from accrual accounting for accurate financial and GAAP compliance.
- Conducting a one-quarter parallel comparison helps determine if the cash or accrual method better reflects the business’s true performance and cash flow.
- Most small business owners should consult with a CPA before switching methods, especially to understand tax implications and ensure proper implementation.
Table of Contents
- What Is Cash-Basis Accounting?
- What Is Accrual-Basis Accounting?
- Cash vs Accrual Accounting: The Practical Differences
- Pros and Cons of Cash-Basis Accounting
- Pros and Cons of Accrual-Basis Accounting
- How to Choose the Right Accounting Method for Your Small Business
- Switching From Cash to Accrual: What the IRS Requires
- How Kelliworks Helps You Pick and Implement the Right Method
- What Actually Matters in the Cash vs Accrual Decision
- Get Help Choosing or Switching Your Accounting Method
- Where to Verify These Rules Yourself
- Sources
- FAQ
What Is Cash-Basis Accounting?
Cash-basis accounting is the simplest way to keep books: you record a sale when the customer’s payment hits your account, and you record an expense when you actually pay the bill. There’s no ledger tracking what customers owe you or what you owe vendors. You just watch the bank balance.
This method is popular with:
- Sole proprietors and single-member LLCs
- Freelancers and independent consultants
- Small service businesses without inventory (salons, cleaning companies, consultants)
- Any owner who wants bookkeeping they can manage without a dedicated finance team
Here’s how the timing plays out. Say you invoice a client $5,000 in December but they don’t pay until February. On cash-basis, that $5,000 shows up as February income, not December, even though the work was finished months earlier. Your December books look leaner than the business actually was that month. It’s a small distortion for a business with a handful of clients, but it can swing your numbers significantly if you’re juggling several large invoices at once. The upside is real, though: no accounts receivable or accounts payable to reconcile, and your reported profit tracks your actual bank balance almost exactly.
What Is Accrual-Basis Accounting?
Accrual-basis accounting records revenue when it’s earned and expenses when they’re incurred, not when the cash moves. This is the method Generally Accepted Accounting Principles (GAAP) require, and it’s built around the matching principle: revenue gets paired with the expenses that generated it in the same period, so the resulting financial statements reflect economic reality rather than bank timing.
Accrual accounting tends to show up in:
- Businesses that carry inventory or sign long-term contracts
- Companies seeking outside investors or bank financing
- Any business preparing GAAP-compliant statements for lenders or auditors
- Growing companies that need month-over-month performance visibility
Picture a contractor who completes a $20,000 project in November but invoices and collects payment in January. Under accrual, that $20,000 counts as November revenue, matched against the labor and materials cost from that same month. The books show the true performance of November, even though no cash arrived until the new year. That accuracy comes with more work: you need active accounts receivable and accounts payable tracking, plus month-end adjustments for accrued expenses and deferred revenue.
Cash vs Accrual Accounting: The Practical Differences
The choice between cash basis vs accrual basis comes down to five factors that actually change how you run the business day to day.
| Factor | Cash-basis | Accrual-basis |
|---|---|---|
| Timing of recognition | When cash is received or paid | When revenue is earned or expense incurred |
| Tax timing | Income taxed when collected | Income taxed when earned, even if uncollected |
| GAAP compliance | Not GAAP-compliant | Required for GAAP reporting |
| Bookkeeping effort | Low; no AR/AP tracking | Higher; requires AR/AP and month-end adjustments |
| Best for | Freelancers, service businesses, sole proprietors | Inventory-based businesses, companies seeking financing |
The tax timing row is where owners get caught off guard. Under accrual, you can owe tax on income you haven’t collected yet, which is exactly why tax professionals stress cash-flow planning for any business on this method. Cash-basis avoids that problem entirely since nothing is taxable until it’s in the bank, but it can also make a profitable quarter look thin on paper if big invoices are still outstanding.
Pros and Cons of Cash-Basis Accounting
Cash-basis wins on simplicity. You can see exactly where you stand by checking the bank balance, and you don’t need software or a bookkeeper to interpret it. It also lets you defer taxable income: if a client pays you in January instead of December, that income shifts into next year’s tax return.
- Pro: Direct visibility into your actual cash position
- Pro: Taxable income can be deferred simply by delaying collection
- Con: Doesn’t show money owed to you or money you owe others
- Con: Makes financial planning harder when invoices are large or irregular
The catch shows up when customers pay late or when you need financing. A bank reviewing cash-basis statements sees a business that looks slower than it is, because completed work sitting in unpaid invoices doesn’t appear anywhere.
Pro Tip: If you invoice in large, irregular chunks, run a quick side calculation of your outstanding receivables each quarter. It won’t change your tax method, but it will keep you from mistaking a slow cash month for a slow business month.
Pros and Cons of Accrual-Basis Accounting
Accrual accounting gives you the fuller picture. Revenue and the expenses tied to it land in the same period, so your income statement actually reflects how the business performed, not just what hit the bank. That’s why lenders and investors generally require it before extending credit or writing a check.
- Pro: Matches revenue to related expenses for an accurate performance view
- Pro: Meets GAAP and satisfies most lender and investor due diligence
- Con: Requires more bookkeeping, including AR/AP tracking and adjusting entries
- Con: Can create cash-flow surprises since reported profit isn’t the same as cash on hand
The trade-off is discipline. Without consistent month-end controls, accrual books drift from reality fast, and you can end up owing taxes on revenue that’s still sitting in a client’s unpaid invoice.
How to Choose the Right Accounting Method for Your Small Business
Run through this checklist before deciding, and don’t guess on the parts tied to tax law.
- Determine if inventory is a material part of your income. IRS Publication 538 generally requires accrual accounting for purchases and sales when inventory drives income, with limited exceptions for smaller operations.
- Ask whether lenders or investors will need GAAP-compliant statements. If you’re courting outside capital, accrual is close to non-negotiable.
- Measure your receivable and payable cycles. Businesses collecting payment in 30 days or less feel less pain from cash-basis distortions than those waiting 60 to 90 days.
- Run a one-quarter test. Keep both sets of books briefly and compare the resulting profit pictures before committing to a permanent switch.
Pro Tip: If step five shows your cash-basis and accrual numbers diverging by more than a small margin, that gap is usually receivables sitting unpaid. It’s worth a conversation with a CPA before your next tax filing, not after.
Switching From Cash to Accrual: What the IRS Requires
Changing your accounting method for tax purposes isn’t as simple as flipping a switch in your software. You need to file IRS Form 3115, the formal application for a change in accounting method, and get it approved before the new method applies to your tax return.
- The switch typically triggers a Section 481(a) adjustment, which accounts for the cumulative difference between your old and new method and can create a one-time taxable or deductible item
- Timing the change at the start of a fiscal year keeps the transition cleaner and easier to model
- Update your accounting software’s chart of accounts and AR/AP processes before the new period begins, not mid-stream
- Businesses that cross the IRS gross-receipts ceiling or add inventory as a material income factor may be required to switch, not just eligible to
A recommended sequence, drawn from common professional practice, is to run parallel books for one quarter, model the 481(a) adjustment with a tax advisor, then file Form 3115 with enough lead time before your filing deadline.
How Kelliworks Helps You Pick and Implement the Right Method
Kelliworks works through this decision with small business owners every week. Our bookkeeping and accounting team handles the revenue and inventory review, prepares Form 3115 filings when a switch makes sense, and builds out cash-flow forecasting so accrual reporting doesn’t catch you off guard at tax time. A typical engagement starts with an assessment of your gross receipts and receivable cycles, moves to a clear recommendation, and ends with your books set up correctly from day one.
What Actually Matters in the Cash vs Accrual Decision
Most articles on this topic treat cash and accrual as a coin flip based on personal preference. It isn’t. The IRS gross-receipts threshold and the inventory rule aren’t suggestions. If you’re under $32 million in receipts and carry no material inventory, you genuinely get to choose, and that choice should follow your cash cycle, not a generic recommendation you found online.
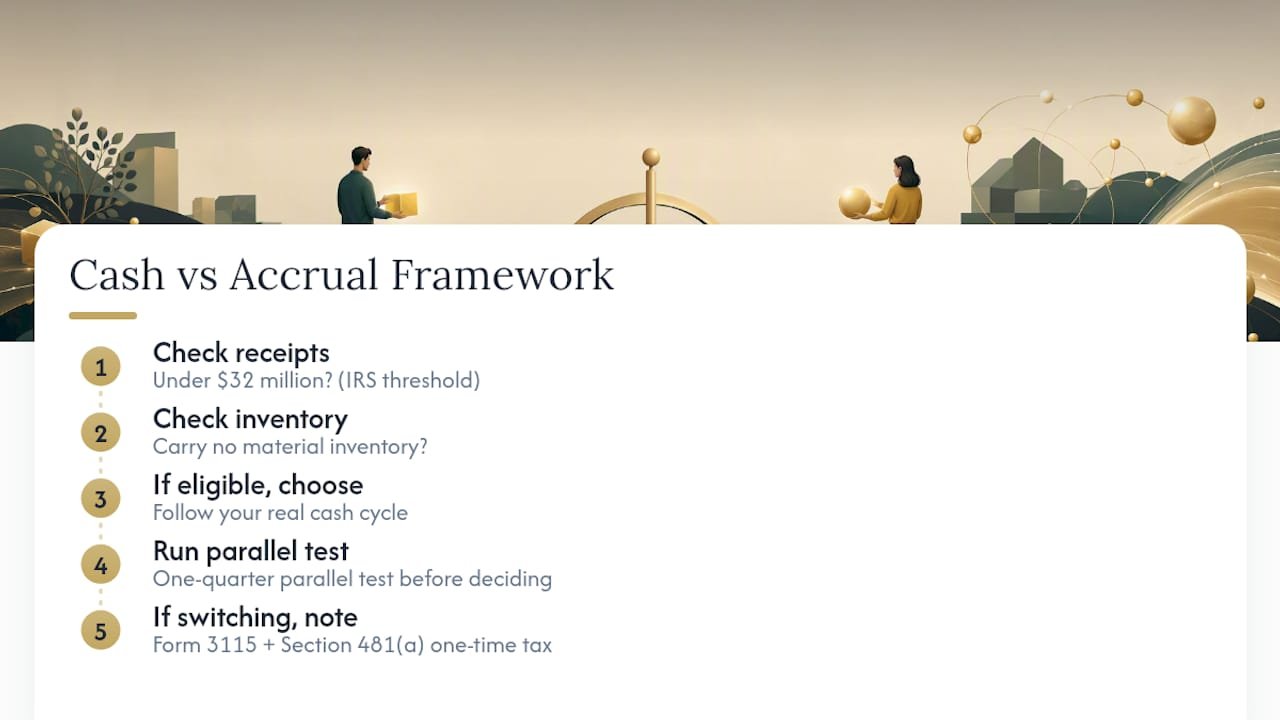
Where the conventional advice falls short is the switching conversation. Plenty of guides tell you “accrual is better for growth” without mentioning that Form 3115 and a Section 481(a) adjustment can create a real, one-time tax bill the year you switch. That detail changes the calculus for a business deciding whether to make the move this year or next.
Prioritize this: run the one-quarter parallel test before you decide anything permanent. Numbers on a spreadsheet are cheap to generate and will tell you more about your real cash cycle than any article, including this one.
— Kelli
Get Help Choosing or Switching Your Accounting Method
Picking the right method is one decision. Implementing it correctly, filing the paperwork, and keeping your books clean afterward is another matter entirely, and it’s where most owners run out of time. Some service providers act as outsourced accounting departments, helping clients interpret IRS thresholds and Section 481(a) adjustments so they don’t have to manage these technical details alone.
Our initial assessment covers three things: a gross-receipts check against the IRS threshold, a review of whether inventory or long-term contracts affect your recognition timing, and a look at your receivable and payable cycles to see how much distortion cash-basis is actually creating. From there, we recommend a method, and if a switch is warranted, we handle the tax preparation and filing work that goes with it, including Form 3115 coordination. You can schedule a consultation directly to get that assessment started this week.
Where to Verify These Rules Yourself
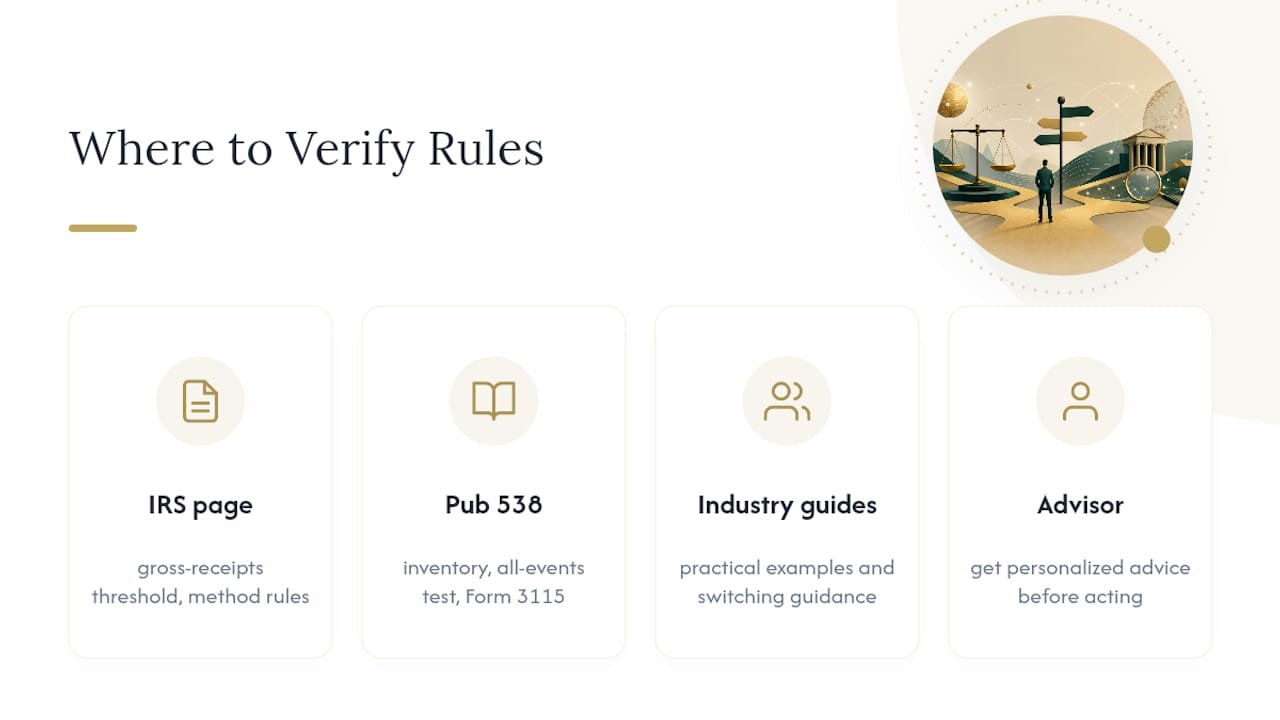
The IRS accounting methods page covers the gross-receipts threshold and general method rules, while IRS Publication 538 goes deeper into inventory requirements, the all-events test, and Form 3115 procedures. Industry guides from Stripe, QuickBooks, and Bank of America provided the practical examples and switching guidance referenced throughout this article.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Publication 538 (Accounting Periods and Methods) | IRS
- Cash vs. accrual accounting | Stripe Resources
- Cash vs Accrual Accounting? What are the main differences a business should know in 2026 | QuickBooks
- Cash vs. accrual accounting: What’s best for my small business? | Bank of America Business
FAQ
Can a Small Business Use Cash-Basis for Taxes and Accrual for Investors?
Yes, many small businesses file taxes on cash-basis while keeping a separate accrual set of books for internal reporting or investor updates. This is common practice as long as you’re consistent within each set of records and disclose your tax method properly.
What Is the IRS Revenue Threshold That Forces Accrual Accounting?
Businesses averaging more than $32 million in gross receipts are generally required to use accrual accounting, based on the 2026 inflation-adjusted threshold. Below that level, most small businesses can choose either method unless inventory rules apply.
Do I Need Accrual Accounting if I Carry Inventory?
Generally, yes. IRS Publication 538 requires accrual accounting for purchases and sales when inventory is a material income-producing factor, though some smaller businesses qualify for exceptions.
How Do I Switch From Cash to Accrual Accounting?
You file IRS Form 3115 to formally request the method change, which typically triggers a Section 481(a) adjustment for the cumulative difference between methods. Timing the switch at the start of a fiscal year keeps the transition cleaner.
Does Kelliworks Help With Choosing an Accounting Method?
Yes, Kelliworks reviews your gross receipts, inventory situation, and cash cycles as part of an initial assessment, then recommends the method that fits and handles the accounting and bookkeeping setup. Pricing for services isn’t published; current rates are available directly through Kelliworks.