
If you found an error on a filed business return, you likely need Form 1120-X for a corporation, Form 941-X for payroll tax corrections, or an Administrative Adjustment Request (AAR) for a partnership under the centralized audit regime. Start by gathering your original return, the corrected documents, and a clear written explanation of what changed. Most amendments must be filed within three years, though some situations carry different windows.
TL;DR:
- If you catch an error before the original deadline, including extensions, a superseding return can replace the filing; after that, amend it.
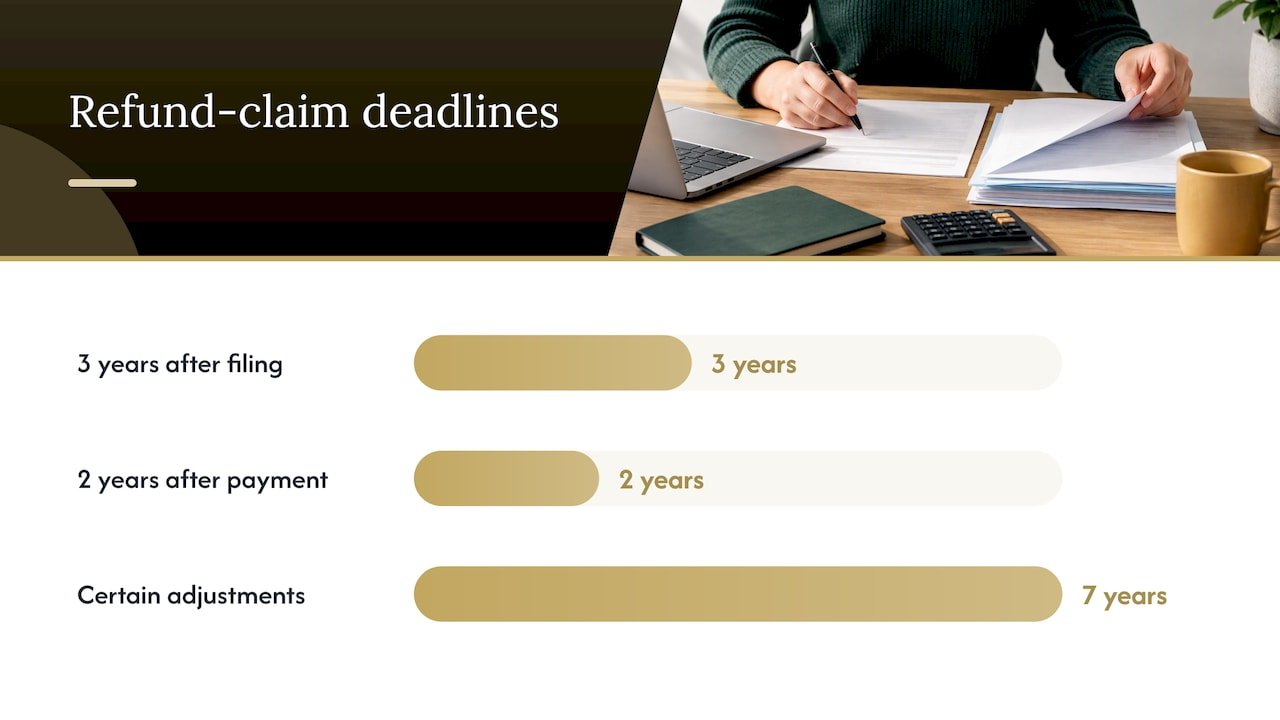
- Refund claims generally fall due three years after filing or two years after payment, whichever is later; bad debts and worthless securities allow seven years.
- Payroll corrections require a separate filing for each affected quarter, and refund claims may need employee repayment records or consent before the employer can proceed.
- A federal correction can trigger a separate state amendment; requirements vary, so check each state’s rules and retain paired federal and state filing records.
- BBA partnerships file an AAR within three years of filing or the original due date, whichever is later, and should coordinate revised partner tax schedules.
Table of Contents
- When to file an amended business return: triggers for small businesses
- Which amended form to use for your business type
- Deadlines and timing you need to track
- How to prepare and file an amended return correctly
- State and local amendments triggered by a federal correction
- Payroll corrections: using Form 941-X the right way
- Partnerships and the BBA regime: AAR versus amended returns
- What happens after you file an amended business return
- What we see most often, and how to avoid repeat amendments
- How we help with amended returns, payroll corrections, and state filings
- FAQ
- Sources
When to file an amended business return: triggers for small businesses
Not every mistake calls for an amended return, and knowing the difference saves you time and paperwork. Some errors affect your tax liability directly; others are informational and may not require a full amendment.
Here are the most common reasons small businesses amend a filed return:
- You missed a deduction or credit, such as a research and development credit or depreciation you forgot to claim.
- You received a corrected W-2c or a corrected 1099 after you already filed, which changes reported income or wages.
- You discover unreported income that changes your taxable income for the year.
- You need to change an accounting method or make a late election that the IRS requires through an amended filing.
One distinction trips up a lot of business owners: a superseding return is different from an amended return. If you catch the error before your original filing deadline, including extensions, you can often file a superseding return instead, which replaces the original filing rather than correcting it after the fact. Once that deadline passes, you are in amended-return territory.
The quickest way to decide whether you need to act is to ask whether the change affects a line on your tax computation, like income, deductions, or credits, versus a line that is purely informational. A changed address or a corrected officer name usually does not require an amendment. A changed income figure almost always does.
Pro Tip: Before filing anything, confirm whether you are still inside your original due date. If you are, a superseding return is often simpler than an amendment.
Which amended form to use for your business type
Picking the right form the first time keeps your correction moving instead of sitting in a processing queue. The form depends on your entity type and what triggered the correction.
- C corporations use Form 1120-X to correct an originally filed corporate return, attaching supporting schedules for missed deductions, carrybacks, or accounting method changes.
- S corporations generally reference the same 1120-X instructional framework when the correction flows through to shareholder reporting, though most S corporation corrections start with an amended Form 1120-S and corrected Schedules K-1.
- Partnerships under the Bipartisan Budget Act (BBA) regime typically file an Administrative Adjustment Request rather than a traditional amended partnership return, while partnerships outside that regime may still use Form 1065 or 1065-X.
- Employers correcting payroll tax use Form 941-X, filing a separate form for each affected quarter.
- Partners and S corporation shareholders often need to file their own Form 1040-X once corrected Schedule K-1 information reaches them, since pass-through items flow to personal returns.
Mixing these up, filing an amended partnership return when an AAR was required, for example, is one of the more common and avoidable errors we see among business owners handling this on their own.
Deadlines and timing you need to track
The statute of limitations determines whether the IRS will even accept your amended return or refund claim, so timing matters as much as accuracy. The general rule under Form 1120-X instructions is that a corporation must file within three years after the date it filed the original return, or within two years after it paid the tax, whichever gives more time, when claiming a refund. Certain adjustments, including those tied to bad debts or worthless securities, carry a longer seven-year window.
Partnerships filing an AAR face their own clock: the deadline is three years from the date the partnership return was filed, or its original due date, whichever is later, according to IRS guidance on BBA partnerships.
A few timing points worth building into your process:
- Filing before your original due date may qualify you for a superseding return instead of an amendment.
- Carryback claims often follow different timing rules than standard refund claims, so check the specific form instructions.
- Missing the window means forfeiting a refund claim entirely, even if the underlying error is clear.
How to prepare and file an amended return correctly
A clean amendment moves faster through IRS review, and most rejections come from preventable gaps rather than complicated tax issues. Work through these steps in order.
- Pull your original return and every corrected source document, including any W-2c or corrected 1099 forms tied to the change.
- Write a clear, specific explanation of what changed, referencing the exact line numbers from your original return rather than a general summary.
- Attach every required schedule, including Form 8886 for reportable transactions or supporting pages for carryback claims.
- Confirm whether your form can be e-filed through the IRS Modernized e-File system or must be mailed as a paper form, since not every amended business form supports e-filing.
- Double-check your business name, EIN, and tax year selection before submitting, since mismatches are among the most common rejection triggers.
The IRS notes that incorrect attachments or vague explanations of changes are a frequent cause of processing delays on amended corporate filings, and that the amended data should mirror your corrected return precisely rather than summarizing it loosely.
Pro Tip: Keep your explanation of changes short and line-specific. “Corrected depreciation on line 20 from $12,000 to $18,400 per revised fixed asset schedule” moves through review faster than a paragraph of context.
State and local amendments triggered by a federal correction
A federal amendment rarely stays federal. Most states calculate taxable income starting from your federal figures, so a change at the federal level often changes what you owe your state too.
- Check your state’s specific guidance on amended returns once your federal correction is final, since requirements vary by state.
- File a separate state amended return where required, even if the state eventually adopts your federal adjustment.
- Keep copies of both the federal and state filings together, since auditors on either side may ask for the paired documentation.
- Some states accept a federal adjustment automatically, while others require their own amended form regardless of what the IRS already corrected, according to IRS guidance on filing amended returns.
If your business operates in more than one state, or your correction involves apportionment, this is a good point to loop in your accounting partner rather than guessing at each state’s process separately.
Payroll corrections: using Form 941-X the right way
Payroll tax corrections follow a different set of rules than income tax amendments, and getting the process wrong can delay a refund or trigger additional review.
- File a separate Form 941-X for each quarter affected, since you cannot combine corrections across quarters on one form.
- Choose between the adjustment process and the claim process depending on whether you underreported or overreported the tax, since the instructions treat these differently.
- If you are claiming a refund or abating an overreported amount for certain taxes, be ready to provide the required certifications, which can include documentation of employee repayment or consent.
- Issue a corrected W-2c where wages changed, update your payroll records, and document any communication with affected employees.
Employment tax corrections also run on their own period of limitations, so a payroll fix and an income tax amendment for the same year may need separate timing checks rather than one shared deadline.
Pro Tip: If a payroll correction affects both the employer and employee side of taxes, confirm the employee consent requirements before filing a refund claim, since missing certification is a common reason these get kicked back.
Partnerships and the BBA regime: AAR versus amended returns
Partnerships correcting a filed return face a different system than corporations do, and the wrong choice here can shift who ends up paying the tax. Under the centralized partnership audit regime, the IRS generally assesses adjustments at the partnership level rather than chasing down individual partners, which changes how corrections should be handled.
- Partnerships subject to BBA file an Administrative Adjustment Request instead of a standard amended partnership return.
- The AAR deadline is three years from the date the partnership return was filed, or its original due date, whichever is later.
- Coordinate corrected Schedules K-1 with every partner before filing, since each partner’s reporting depends on accurate, updated figures.
- Partnerships that opted out of BBA, or that fall outside its scope, may still use a traditional amended Form 1065 instead.
Given how much turns on which regime applies to your partnership, this is one area where involving tax counsel or an experienced document preparation company in San Diego early tends to prevent costly rework later.
What happens after you file an amended business return
Once your amendment is submitted, patience and tracking matter more than follow-up calls. You can monitor status through the IRS “Where’s My Amended Return” tool and related IRS resources.
- Expect processing to take time, and plan your cash flow as though a refund will arrive later rather than sooner.
- Outcomes vary: you may receive a refund, owe additional tax with interest, or get selected for further review.
- Respond promptly to any IRS notice, and loop in a tax professional if the notice raises questions you cannot answer with your existing documentation.
- Keep your amendment file, original return, corrected documents, explanation of changes, and proof of filing, in one place in case the IRS requests more information later.
What we see most often, and how to avoid repeat amendments
The amendments that cause the most friction almost always trace back to a vague explanation of changes or a missing attachment, not a complicated tax question. We find that businesses with organized source documents and a habit of reviewing payroll and 1099 data before filing rarely need to amend more than once for the same issue. Catching errors early, rather than after filing, is the real fix.
— Kelli
How we help with amended returns, payroll corrections, and state filings
Filing an amended business tax return on your own means tracking form selection, deadlines, and attachments while running your business at the same time. Our tax preparation and filing team reviews your original return and corrected documents, prepares the amendment with the explanation of changes the IRS expects, and coordinates any related payroll correction or state filing through our accounting services.
- The process includes reviewing the original filing and corrected documents before preparing anything.
- Preparation of the amended federal form and coordination of any required state amendment.
- Handling payroll correction filings alongside income tax amendments when both are needed.
An engagement with us starts with a document review, moves to a clear timeline for your specific form, and ends with the completed filing and a copy for your records. If you are dealing with a correction right now, schedule a consultation and we will walk through what your specific situation needs.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What are the rules for filing an amended tax return?
You generally must file within three years of your original filing date or two years of paying the tax, whichever gives more time, according to Form 1120-X instructions. The return needs a clear explanation of what changed, referencing the original line numbers, along with any supporting schedules.
How long does it take the IRS to process an amended return?
Processing time varies and can span several months depending on the complexity of the correction and the completeness of your attachments. You can track status through the IRS “Where’s My Amended Return” tool rather than waiting without visibility.
Is there a penalty for amending your tax return?
Amending itself does not trigger a penalty, but if the correction shows you owe additional tax, interest applies from the original due date and penalties may apply depending on the circumstances. Filing the correction as soon as you identify the error generally limits how much interest accrues.
Is it a red flag to amend a tax return?
Filing an accurate amended return is a normal, expected part of tax compliance and is not inherently a red flag. A clear explanation of changes and complete attachments, as outlined in IRS guidance on amended corporate returns, support smooth processing regardless of the reason for the correction.
Sources
- Instructions for Form 1120-X (12/2025) | Internal Revenue Service
- Instructions for Form 941-X (04/2026) | Internal Revenue Service
- File an administrative adjustment request for a BBA partnership | Internal Revenue Service