
Most small business tax mistakes are not exotic. They are ordinary habits: paying personal expenses from the business account, skipping a quarterly payment, putting off the books until March. Each one is avoidable, and each one is cheaper to fix before a return is filed than after. Below are the mistakes we see most often, what the IRS says about them, and what to do instead.
TL;DR
- Separate business and personal money. It is the base of every deduction you claim and every audit you may face.
- Make estimated tax payments on time. A refund at filing does not always protect you from an underpayment penalty.
- Keep records long enough, classify workers correctly, and file every return even if you cannot pay in full.
- Review your whole return before you file, even when a preparer prepared it. You remain responsible for its accuracy.
Table of Contents
- 1. Mixing personal and business finances
- 2. Waiting until tax time to do the bookkeeping
- 3. Missing or underpaying estimated taxes
- 4. Misclassifying workers
- 5. Letting payroll taxes slip
- 6. Leaving legitimate deductions on the table
- 7. Keeping records for too short a time
- 8. Choosing a structure and never revisiting it
- 9. Basic filing errors
- 10. Not filing because you cannot pay
- A quick self-check
- Our view: the cheapest tax fix is a monthly one
- How we can help
- FAQ
- Sources
1. Mixing personal and business finances
The IRS Taxpayer Advocate Service stresses keeping business and personal finances apart and using a dedicated account and card for the business. This is more than tidiness. When a deduction is questioned, your bank and card statements are the first proof you have. If a coffee, a grocery run and a client dinner sit on one card, you have to rebuild the story by hand.
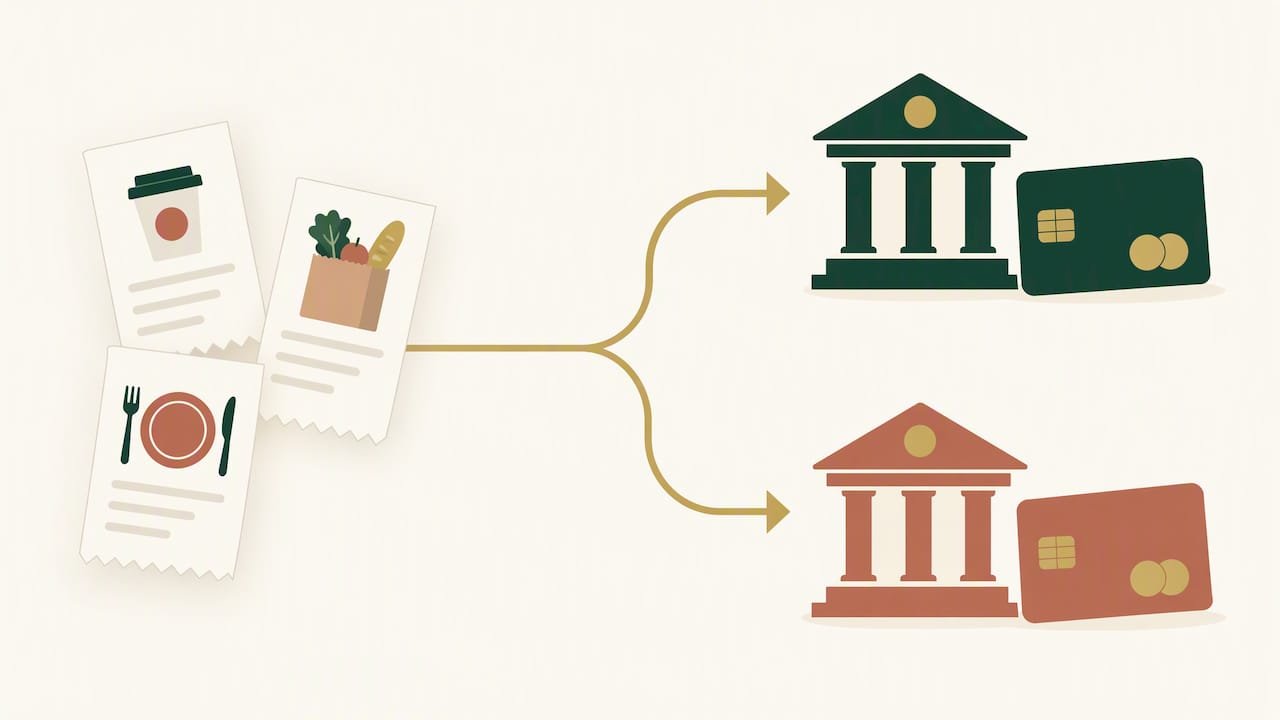
Mixing causes two opposite errors. You miss legitimate deductions because you cannot find them, or you deduct something personal by accident. Both draw attention.
What to do:
- Open a business checking account and a business card in the name of the business.
- Pay yourself with a transfer (a draw or payroll, depending on your structure), never by paying personal bills from the business.
- If you slip and pay a business cost personally, record it as a reimbursement the same week.
We walk through the setup in how to separate personal and business finances. Clean accounts also help outside of tax season. Self-employed owners who apply for a mortgage will find that some lenders qualify borrowers using 12 to 24 months of bank statements instead of tax returns, and that only works well when the statements show a tidy business.
2. Waiting until tax time to do the bookkeeping
Piecing together a year of expenses in March is slow, and it is where deductions get lost. Receipts fade, invoices go missing, and you forget what a $340 charge in June was for.
A light monthly routine fixes most of it:
- Reconcile your bank and card accounts to the books once a month.
- Categorize every transaction, or have someone do it for you.
- Save receipts and invoices digitally as you go.
- Review a profit and loss statement each month, so surprises show up in time to act.
Our guide to bookkeeping best practices for small business owners covers the routine in detail. If you are closing a year and the books are behind, see how to close your books for taxes.
3. Missing or underpaying estimated taxes
There is no employer withholding for most owners. The IRS says individuals, including sole proprietors, partners and S corporation shareholders, generally must make estimated tax payments if they expect to owe at least $1,000 after withholding and credits. For corporations the threshold is $500.
Two points catch people out:
- A refund does not guarantee safety. Paying late or too little during the year can lead to a penalty even if you are due a refund when you file.
- A strong second half does not erase a weak first half. Payments are measured by period, so a lump sum in January does not fix a missed April payment.
A practical habit is to move a fixed percentage of every payment received into a separate tax savings account. We explain the rules for avoiding the penalty in our estimated tax safe harbor guide, and how to build a set-aside system in our tax savings strategy for small business owners.
LLC owners get surprised often. If you take irregular draws and pay nothing during the year, the bill arrives all at once. Our piece on setting payroll and draws for a U.S. LLC shows how to smooth that out.
4. Misclassifying workers
Calling someone a contractor does not make them one. For federal employment taxes, the IRS applies a common law standard, and an employer-employee relationship exists when the business has the right to control what is done and how it is done. A label on an agreement does not decide it.
Warning signs that a “contractor” may be an employee:
- You set their hours and tell them how to do the work.
- They work only for you, using your equipment.
- The relationship is ongoing and open-ended, not project-based.
Misclassification can leave you owing payroll taxes you never withheld. If you are unsure, get a professional opinion before the first payment, not after a notice. For contractors who are correctly classified, you also have reporting duties: see our overview of 1099 filing requirements. Employers should also review our payroll compliance checklist.
5. Letting payroll taxes slip
Payroll taxes are money you hold on behalf of employees and the government. Using them to cover rent in a slow month is one of the most expensive choices an owner can make, because the penalties are among the harshest the IRS applies. Treat payroll tax deposits as untouchable and pay them first.
If you run payroll yourself, set it up carefully from day one. Our guides on setting up small business payroll, payroll taxes and the $100,000 trap and multi-state payroll rules are written for owners who have not done this before.
6. Leaving legitimate deductions on the table
Many owners deduct too little because they think an expense must be indispensable. It does not. According to IRS Publication 583, a deductible expense must be ordinary, meaning common and accepted in your trade, and necessary, meaning helpful and appropriate for your business.
That test is wider than most people assume. Software, professional fees, work-related education and a qualifying home office can all pass it. The test also cuts the other way. Personal costs dressed up as business ones do not pass, which is another reason to keep the accounts separate.
Two habits protect your deductions:
- Write a short note on anything unusual, such as who a meal was with and why.
- Ask your accountant about deductions during the year, not after it closes. Our tax savings strategy guide and cost-saving accounting strategies explain where owners often find savings.
7. Keeping records for too short a time
Many owners keep records for three or four years and then throw them out. For employment taxes, the IRS says to keep records for at least four years after filing the fourth quarter return for the year. Some credits are stricter. The same IRS page points to a longer period for certain credits, such as the Employee Retention Credit, so check the page for any credit you claimed before you delete anything.
A simple rule: store digital copies of tax returns, payroll filings, bank statements, receipts and contracts in a labeled folder by year, and do not purge until you have confirmed the retention period for each category.
8. Choosing a structure and never revisiting it
The form of business you operate determines what taxes you must pay and how you pay them. A sole proprietorship, partnership, LLC, S corporation and C corporation are taxed differently, and the right choice at launch may not be right once revenue grows.
The mistake is treating the choice as permanent. Review it when income changes sharply, when you hire, or when you bring in a partner. A conversation with a tax professional before year end is worth more than an adjustment after it. If you are launching, our early-stage tax planning guide for startup founders lays out what to settle first.
9. Basic filing errors
The IRS lists the same simple errors every year. Its guidance on common tax return mistakes includes:
- the wrong filing status;
- inaccurate income figures;
- misspelled names;
- missing taxpayer identification numbers, such as an SSN or EIN;
- an unsigned return, which is not valid.
The IRS also recommends e-filing, because the system often catches these errors before the return is rejected. Its checklist of common errors is worth reading before you submit anything. The checklist notes that you should review the entire return even if someone else prepared it.
That last point matters. The IRS is clear that owners remain responsible for the accuracy of their returns whoever prepares them, so confirm that your preparer signs and includes a Preparer Tax Identification Number (PTIN).
10. Not filing because you cannot pay
Fear of the bill makes some owners skip the return altogether. That usually makes things worse. The IRS advises that you file all returns that are due whether or not you can pay in full. If you owe, you can then look at payment options.
Past-due returns carry a second cost. The IRS may hold a refund when returns are outstanding, so filing matters even when you expect money back.
If you cannot finish on time, a filing extension gives you more time to file, though not more time to pay. See business tax extension forms, deadlines and payments. If you have already made an error, our guide to amended business tax returns explains which forms apply.
A quick self-check
| Question | If the answer is no |
|---|---|
| Do you have a business-only bank account and card? | Open them this month |
| Are your books reconciled through last month? | Schedule a monthly review |
| Have you paid your estimated taxes on time this year? | Calculate what is owed now |
| Are all workers correctly classified? | Get a professional opinion |
| Are payroll tax deposits current? | Pay them before anything else |
| Do you know how long to keep each record? | Check before you discard |
| Have you filed every return that was due? | File the late ones first |
Our view: the cheapest tax fix is a monthly one
We work with small business owners, freelancers and startups, and the pattern is consistent. Owners rarely get into trouble because the tax code is too hard. They get into trouble because nobody looked at the numbers between filings.
The businesses that feel calm in March have three things in common. Their accounts are separate. Their books are current within a few weeks. Someone has told them, before the quarter ends, roughly what they will owe. None of this needs a large team. It needs a routine and a person who owns it.
We would also say that you do not have to choose between doing it all yourself and handing everything off. Some owners want a bookkeeper and a planning call each quarter. Others want a full outsourced department. Both are reasonable. What matters is that the work is done on a schedule, not under deadline pressure.
— Kelli
How we can help
If you want these mistakes handled for you, our full-service accounting and bookkeeping team keeps your books current, supports payroll and builds the reports you need to plan. For returns, see our tax preparation and filing service. If you have outstanding returns to file, the page lists a one-off $150 deposit for them. Not sure where to begin? Book a consultation and we will look at your situation together.
FAQ
What is the most common small business tax mistake?
Mixing personal and business finances is one of the most common, and it affects everything else. It makes bookkeeping harder, hides deductions and weakens your proof in an audit. A dedicated account and card is the simplest fix.
What happens if I file my business taxes incorrectly?
Small errors, such as a misspelled name or missing number, can delay processing or cause a rejection. If you find a mistake after filing, you may need to submit an amended return. We explain the forms in our amended business tax return guide. A tax professional can tell you which applies to your return.
Can I owe an estimated tax penalty if I get a refund?
Yes. The IRS says late or insufficient estimated payments can bring a penalty even when you are due a refund at filing. Payments are judged through the year, not only at the end.
Does hiring a tax preparer remove my responsibility?
No. The IRS says you are ultimately responsible for the accuracy of your return. Check that the preparer signs it and lists a PTIN, and review the return yourself before it is filed.
Sources
- Small business tax highlights, IRS Taxpayer Advocate Service
- Common tax return mistakes to avoid, IRS
- Topic no. 303, Checklist of common errors, IRS
- Filing past due tax returns, IRS
- Employment tax recordkeeping, IRS
- Publication 583, Starting a Business and Keeping Records, IRS
- Employer-employee common law standard, IRS information letter