
Yes, QuickBooks can track inventory. QuickBooks Online offers built-in tracking on its Plus and Advanced plans, and QuickBooks Desktop offers Advanced Inventory through Enterprise. The core workflow stays consistent across both: turn on tracking, add your products with starting quantities, then let invoices, purchase orders, and bills adjust your counts automatically. Advanced features like multi-site tracking or barcode scanning usually require Enterprise or a third-party add-on.
TL;DR:
- QuickBooks Online inventory tracking is limited to Plus and Advanced plans, requiring an upgrade from Simple Start or Essentials before activation.
- It is crucial to set a firm “As of” date and accurately map your inventory asset account before entering any initial quantities to ensure data accuracy.
- Inventory updates automatically through sales, purchases, and receipts, but manual adjustments should only be used for physical shrinkage or losses, not data entry errors.
- QuickBooks’ built-in tools suit small-scale operations but are limited for multi-location, barcode scanning, or serial tracking needs, which may require Enterprise or add-ons.
- Proper setup, regular reconciliation, and disciplined bookkeeping habits are essential to keep inventory numbers reliable and protect financial statement accuracy.
Table of Contents
- What You Need Before Turning On QuickBooks Inventory Tracking
- How to Turn On Inventory Tracking in QuickBooks Online
- Adding Inventory Products the Right Way
- How Sales and Purchase Orders Update Your Inventory Counts
- When to Use Inventory Adjustments (and When Not To)
- Reports That Tell You What’s Really Happening With Stock
- Where QuickBooks Inventory Tracking Hits Its Limits
- KelliWorks’ Checklist for Reliable Inventory Accounting
- Why Inventory Accuracy Is a Financial Health Issue, Not Just an Operations One
- How KelliWorks Helps You Get Inventory Tracking Right the First Time
- Sources
- FAQ
What You Need Before Turning On QuickBooks Inventory Tracking
Rushing into inventory tracking without prep work is the fastest way to end up with numbers you don’t trust. Before you touch a single setting, get these pieces in order.
First, confirm your plan supports it. Inventory tracking in QuickBooks Online is available only on Plus and Advanced; Simple Start and Essentials users need to upgrade before the feature even appears in their settings menu. If you’re weighing which plan makes sense for a growing business, our guide to QuickBooks setup for startups walks through the tradeoffs plan by plan.
Once your plan is confirmed, gather this before you start:
- Your inventory asset account. Decide which account will hold the value of your on-hand stock, since every item you add will map to it.
- A firm “As of” date. This is the exact date your starting quantities are true, and it anchors your opening inventory value.
- A clean SKU list. Include starting counts, reorder points, vendor costs, and product categories for every item you plan to track.
- A backup of your company file. If you’re on Desktop, back up before flipping any inventory settings.
If this is your first time turning on inventory tracking, loop in a QuickBooks ProAdvisor or your bookkeeper. Mistakes made in the first hour of setup tend to compound for months.
How to Turn On Inventory Tracking in QuickBooks Online
Enabling QuickBooks inventory tracking takes about five minutes once your prep work is done. Here’s the exact path:
- Go to Settings (the gear icon) and select Account and settings.
- Click the Sales tab.
- Find the Products and services section and select Edit.
- Turn on Show Product/Service column on sales forms.
- Turn on Track quantity and price/rate.
- Turn on Track inventory quantity on hand.
- Click Save, then Done.
Once this is active, a new “Inventory” item type appears whenever you create a product in Products and services, and QuickBooks starts showing on-hand quantities on every relevant sales form.
If you’re still on Simple Start or Essentials, none of these toggles will appear. You’ll need to upgrade to Plus or Advanced first, which you can typically do directly from your QuickBooks account settings without losing existing data.
Pro Tip: Turn this setting on before you create any inventory items, not after. Items built before tracking is enabled sometimes need to be recreated rather than edited, which creates duplicate records you’ll have to clean up later.
Adding Inventory Products the Right Way
Every inventory item you create becomes a permanent record tied to your books, so getting the fields right the first time saves hours of cleanup later. Navigate to Sales → Products and services → New, then select Inventory as the type.
You’ll be asked to fill in:
- Name and SKU: Use a consistent naming convention across your entire catalog. Mixing formats (some items with SKUs, some without) is one of the most common causes of duplicate or “ghost” inventory records.
- Category: Groups similar items for cleaner reporting later.
- Initial quantity on hand and As of date: This must match your physical count on the exact date you specify. Enter it once. Entering an opening quantity and then adjusting it again days later to “true it up” is how businesses end up with inaccurate cost of goods sold from day one.
- Reorder point: The quantity that triggers a low-stock alert.
- Inventory asset account: The account this item’s value flows into.
- Sales price and cost: Used for invoices, sales receipts, and purchase orders.
Non-inventory items (services, or physical goods you don’t track quantities for) use a different item type and won’t show up in your Inventory Summary report. Bundles, which group multiple inventory items into one sellable unit, need to be built carefully since QuickBooks handles the underlying quantity math differently depending on your plan. If you’ve created an item under the wrong type, you generally can’t convert it directly; you’ll need to inactivate the original and create a new item correctly.
How Sales and Purchase Orders Update Your Inventory Counts
Inventory numbers in QuickBooks move automatically based on the transactions you enter, which is exactly why using the right transaction type matters more than it seems. Here’s the sequence for a typical restock cycle:
- A customer buys a product. You create an invoice or sales receipt, and QuickBooks Online reduces the on-hand quantity for that item automatically.
- Stock gets low. You create a purchase order for your vendor, which shows the item as “on order” without touching on-hand quantity yet.
- The shipment arrives. You receive the inventory in QuickBooks, which moves the quantity from “on order” to “on hand.”
- The vendor bill arrives. You convert the purchase order into a bill (or enter the bill separately), which posts the actual cost against your inventory asset account.
If a shipment arrives partially, you can receive just what showed up and leave the remainder open on the PO for the next delivery. Vendor price variances between the PO and the final bill should be corrected on the bill itself, never patched over with a manual adjustment afterward. The Products and Services list shows both on-hand and on-order quantities side by side, which makes it easy to see what’s actually in the warehouse versus what’s simply promised. Reorder points combined with low-stock alerts do the heavy lifting of telling you when to act, so you’re not manually scanning spreadsheets every week.
When to Use Inventory Adjustments (and When Not To)
Inventory adjustments exist for one job: correcting your books to match a physical count that no longer matches what QuickBooks thinks you have. Shrinkage, spoilage, theft, and damage are legitimate reasons to adjust. A pricing error on a bill, a receiving mistake, or a duplicate item entry are not.
This distinction matters because of how adjustments post. When you adjust a quantity, QuickBooks moves value between your inventory asset account and either an Inventory Shrinkage account or another expense/COGS account you choose. That shift hits your balance sheet and income statement directly. Practitioner guidance consistently warns that frequent or improper adjustments distort cost of goods sold and make your financials unreliable.
When a receiving error or a bill mismatch is the real problem, the fix is to trace the chain back: the purchase order, the receipt, and the bill. Correct the original transaction there. Using an adjustment to paper over a data entry mistake just buries the error one layer deeper.
If you’re reconciling inventory against invoices regularly, this guide to inventory and invoice reconciliation covers the same principle from a slightly different angle.
Pro Tip: Document every adjustment with a reason, even a one-line note. Six months from now, “adjusted 12 units, damaged in shipment, 3/14” will save you a confused afternoon during tax prep.
Reports That Tell You What’s Really Happening With Stock
Three reports do most of the work for day-to-day inventory management, and each answers a different question.
- Inventory Summary answers “what do I have and what’s it worth right now?” It lists every tracked item with quantity on hand, on order, and asset value.
- Inventory Valuation Summary and your Cost of Goods Sold reporting answer “am I actually making money on what I sell?” These two together are how you catch a product that looks like a bestseller but carries margins too thin to matter.
- Sales by Product/Service (often called a “best sellers” view) answers “what should I reorder first?” It ranks items by revenue or quantity sold over a chosen period.
A quick math check worth running monthly: compare your Inventory Valuation Summary total against the inventory asset balance on your balance sheet. If they don’t match, something in your transaction flow (a missed bill, a stray adjustment) needs tracing before your next close.
Set your reorder points using what these reports show you, not gut instinct. An item selling steadily but hitting zero stock every few weeks needs a higher reorder point or a faster vendor, and the inventory tracking dashboard surfaces low-stock alerts automatically once those points are set correctly.
Where QuickBooks Inventory Tracking Hits Its Limits
QuickBooks Online’s built-in inventory tracking was built for straightforward retail and product businesses, not full warehouse operations. Knowing where it stops is as important as knowing how to use it.
- Multiple locations: QuickBooks Online uses a single inventory asset account by default, which complicates reporting for businesses running more than one warehouse or storefront. QuickBooks Desktop’s Advanced Inventory, available through Enterprise, supports multiple inventory sites with site-specific reorder points, but setup requires switching to single-user mode and mapping opening quantities per site.
- Barcode scanning: QuickBooks Online doesn’t include native barcode scanning. Businesses with high transaction volume typically pair QuickBooks with a dedicated add-on for that piece.
- Lot or serial tracking and complex bundling: These need either Enterprise’s advanced features or a specialized warehouse management tool layered on top.
A short checklist for deciding whether to stay put or add a tool: if you’re running under a few hundred transactions a month from a single location with simple products, QuickBooks Online Plus likely covers you fully. If you’re managing multiple sites, need barcode scanning, or track lots and serials, it’s worth evaluating Enterprise or an integration built for warehouse operations while keeping QuickBooks as your accounting system of record.
KelliWorks’ Checklist for Reliable Inventory Accounting
Getting inventory tracking right isn’t just a QuickBooks setup task. It’s a bookkeeping discipline that protects your financial statements all year.
Before you flip the switch:
- Confirm your plan supports inventory tracking and upgrade if needed.
- Map your inventory asset account and confirm it aligns with your chart of accounts.
- Build your SKU master list with consistent naming before entering a single item.
- Set one firm “As of” date for opening quantities across your entire catalog.
Once you’re live:
- Enter bills and receive shipments promptly. Delayed entry is the number one cause of inventory counts drifting from reality.
- Reconcile your inventory asset account against your Inventory Valuation Summary every month, not once a quarter.
- Reserve adjustments for physical counts only, and never use them to patch a data entry mistake.
If any of this feels like more than your team has bandwidth for, an outsourced bookkeeping partner or a QuickBooks ProAdvisor can take over the ongoing controls while you focus on running the business. Our bookkeeping best practices guide covers the monthly habits that keep these numbers clean long after setup day.
Why Inventory Accuracy Is a Financial Health Issue, Not Just an Operations One
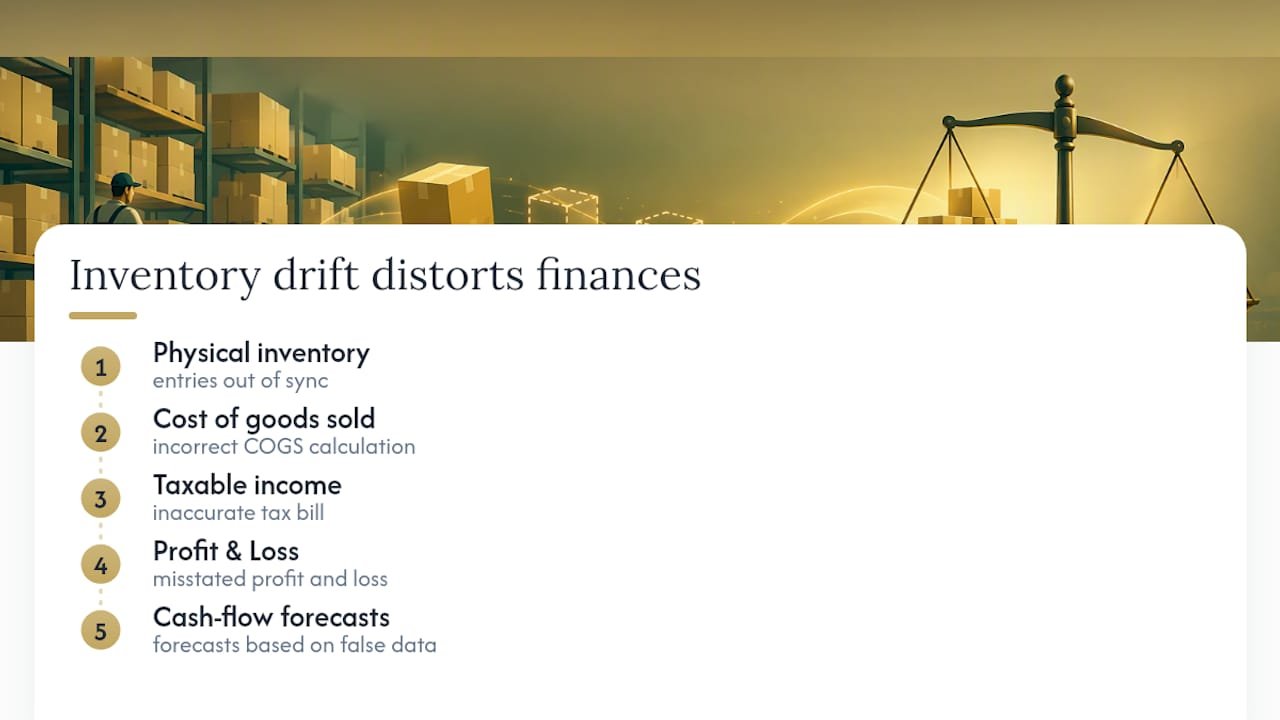
Inventory numbers feed directly into your cost of goods sold, which feeds directly into your taxable income. A business that lets inventory drift out of sync with reality isn’t just risking a messy warehouse count. It’s risking a distorted profit and loss statement, an inaccurate tax bill, and cash-flow forecasts built on numbers that were never true to begin with.
The businesses that handle this well share one habit: they treat inventory entries with the same discipline as bank reconciliations. Every receipt gets entered promptly. Every adjustment gets a reason attached. Nothing gets “fixed” with a shortcut that looks correct on the surface but breaks the audit trail underneath.
If you’re setting up inventory tracking for the first time or suspect your current numbers have drifted, a periodic review with a bookkeeper catches small errors before they become a rebuild.
— Kelli
How KelliWorks Helps You Get Inventory Tracking Right the First Time
Setting up QuickBooks inventory tracking correctly the first time saves you months of correcting mislabeled items, mismatched asset accounts, and adjustment entries that quietly threw off your cost of goods sold. That’s exactly where a dedicated bookkeeping partner earns its keep.
[Image illustrating KelliWorks service offerings]
KelliWorks handles the full setup: choosing the right plan configuration, mapping your inventory asset account correctly, building a clean SKU structure, and establishing the monthly reconciliation habits that keep your on-hand counts matching your books. We also manage the ongoing side, receiving inventory promptly, entering bills accurately, and keeping adjustments reserved for genuine shrinkage rather than data cleanup. Our full-service accounting and bookkeeping services are built for small business owners who want their inventory numbers to actually mean something when tax season or a lender review rolls around. If you’re ready to get your QuickBooks setup handled by people who do this daily, schedule a consultation and we’ll walk through your specific setup together.
Sources
- Set up and track your inventory in QuickBooks Online — QuickBooks
- QuickBooks inventory adjustment guidance — Webgility
FAQ
What is the best way to keep track of my inventory in QuickBooks?
The most reliable method is letting transactions do the work: invoices and sales receipts reduce quantities automatically, while purchase orders converted to bills increase them. Reserve manual adjustments strictly for physical shrinkage or verified loss, and run your Inventory Summary report weekly to catch drift early.
How do you activate inventory tracking in QuickBooks Online?
Go to Settings → Account and settings → Sales, then edit the Products and services section to turn on Track quantity and price/rate and Track inventory quantity on hand. This feature is only available on QuickBooks Online Plus and Advanced, so Simple Start and Essentials users need to upgrade first.
Does QuickBooks have an inventory scanner?
QuickBooks Online doesn’t include native barcode scanning as a built-in feature. Businesses with higher transaction volume typically pair QuickBooks with a dedicated barcode or warehouse management add-on while keeping QuickBooks as their system of record for valuation and accounting.
How do you record inventory items in QuickBooks?
Go to Sales → Products and services → New → Inventory, then fill in the name, SKU, category, initial quantity on hand with an “As of” date, reorder point, and inventory asset account. Getting the opening quantity and asset account right on this first entry matters, since correcting it later is more involved than entering it correctly from the start.
Can KelliWorks help set up QuickBooks inventory tracking for my business?
Yes. KelliWorks handles QuickBooks inventory setup, including plan configuration, asset account mapping, and ongoing reconciliation, as part of its full-service bookkeeping engagements. Pricing is available on request based on your specific setup needs.